Dealing with Credit Card Fraud: Chargebacks and Bank Dispute Forms
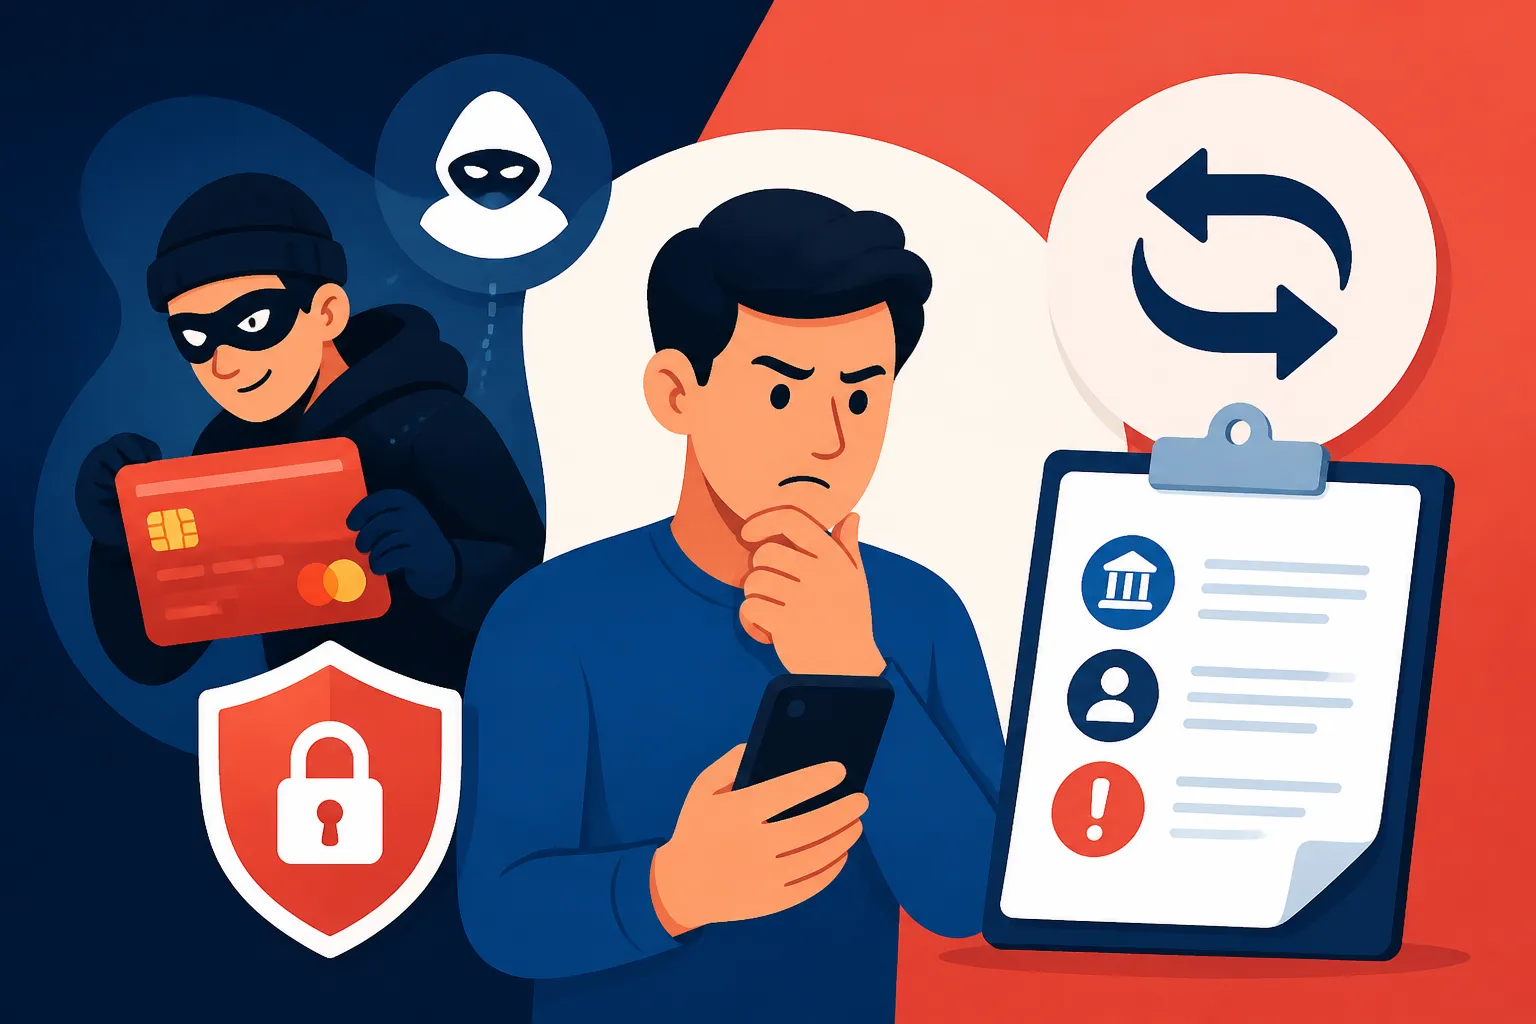
You are sitting at a local hawker center, enjoying a bowl of laksa, when your phone pings with a notification from your bank. You expect it to be the few dollars you just spent, but instead, it is an alert for a $4,500 transaction at a luxury boutique in Paris. That cold spike of adrenaline is something many of us in the expat community have felt. This guide is here to walk you through the exact, high-stress steps of handling credit card fraud in Singapore, from filing the right dispute forms to securing your hard-earned savings.
The Reality of Credit Card Fraud in the Garden City
While Singapore is famously one of the safest cities in the physical world, the digital landscape is a different story altogether. As an expat, you are often a prime target for sophisticated phishing syndicates. We often arrive with foreign numbers, multiple bank accounts, and a general lack of familiarity with how local institutions communicate. I remember when I first moved here, I was constantly bombarded with SMS messages that looked exactly like they were from SingPost or a local bank, urging me to "verify" my details. It is easy to see how even the most tech-savvy professional can slip up.
Fraud in Singapore often takes the form of unauthorized online transactions, card cloning, or social engineering scams. The frustration isn't just about the lost money; it is the feeling of violation and the looming administrative nightmare of getting it back. You might be worried about how this affects your standing with the bank or if you will be held liable for the charges. Validating that frustration is the first step. It is okay to be angry, but we need to pivot to action immediately to ensure your Financial Checklist for Your First 30 Days in Singapore remains on track and your wealth stays protected.
The Monetary Authority of Singapore (MAS) has been pushing banks to implement stricter "Kill Switches" and fraud detection, but the burden of proof often still rests on the consumer. If you do not act within the specific windows provided by your bank—often as short as 14 to 30 days—you might find yourself fighting an uphill battle. Understanding the nuances of Beware of Phishing: How to Avoid Bank SMS Scams in Singapore is your first line of defense, but once the fraud has occurred, the focus shifts entirely to the chargeback mechanism.
Immediate Steps When You Spot an Unauthorized Transaction
The moment you see a transaction you don't recognize, time is your greatest enemy. Do not wait until you get home or finish your meal. The first thing you must do is utilize the "Kill Switch" or "Freeze" function in your banking app. Whether you are with DBS, OCBC, or UOB, most major local apps now have a prominent button to instantly disable your card. This prevents further bleeding. There are cases where a "test charge" of $1 is followed by a $5,000 charge within minutes. Freezing the card stops the sequence in its tracks.
Once the card is frozen, you need to call the bank's 24-hour fraud hotline. Be prepared for a wait; these lines are often busy, but you must stay on the line until you speak to a human. Document the exact time of your call and the name of the representative you spoke with. This is crucial for your records. They will officially "cancel" the card and issue a replacement. If you are traveling or recently arrived, you might worry about how you will access funds in the meantime. This is why having a backup like Wise is essential, as you can often spin up a virtual card instantly while your physical local card is being mailed to you.
After the phone call, you should also consider filing a police report via the Singapore Police Force's e-service portal. While the police may not be able to track down a hacker in a different hemisphere, having an official police report number (NP No.) adds significant weight to your bank dispute. Banks take "unauthorized transaction" claims much more seriously when there is a legal document attached to the claim. It proves you are not merely suffering from buyer's remorse but are a genuine victim of a crime.
Mastering the Transaction Dispute Form and Chargeback Process
The term "chargeback" sounds like financial jargon, but it is simply a request for the bank to forcibly take the money back from the merchant because the transaction was invalid. In Singapore, this process is governed by the rules of the card networks (Visa, Mastercard, or AMEX). To initiate this, you will need to fill out a Transaction Dispute Form. You can usually find these in the "Help" or "Forms" section of your bank's website.
The form will ask you to categorize the dispute. Common categories include:
- Unauthorized Transaction: You never made the purchase and still have the card in your possession.
- Duplicate Processing: You were charged twice for the same item.
- Goods Not Received: You bought something online, but the merchant never delivered.
- Cancelled Subscription: You cancelled a service, but they keep billing you.
For fraud, you will almost always select "Unauthorized Transaction." You will need to provide evidence. If it was a digital purchase, show that you were not on that website. If it was a physical purchase in a different country, your passport stamps or even your Google Maps Timeline showing you were in Singapore at the time can be powerful evidence. When you are Opening a Bank Account in Singapore: Required Documents for Foreigners, you are given a mountain of paperwork; ensure you keep your original account terms, as they outline your liability limits in fraud cases.
| Document Required | Purpose | Tips for Expats |
|---|---|---|
| Completed Dispute Form | Official request to start the investigation. | Be as detailed as possible; don't leave blanks. |
| Police Report (SPF) | Legal backing for your claim. | File this online via Singpass for a faster record. |
| Transaction Alerts | Proof of when you were notified. | Take screenshots of the SMS or App push notification. |
| Proof of Presence | Evidence you weren't at the merchant location. | Use office door logs or Grab ride receipts. |
| Interaction Logs | Proof you tried to resolve it (if applicable). | Keep copies of emails sent to the merchant. |
Dealing with Denied Claims and Complex Scams
Sometimes, the bank might deny your dispute. This usually happens if the transaction was authenticated via a One-Time Password (OTP) sent to your registered mobile number. Under the "Fair Sharing Framework" in Singapore, if a user is found to have been "grossly negligent"—such as giving away their OTP to a scammer—the bank may not be liable for the loss. This is a bitter pill to swallow and one of the most common points of friction for newcomers.
If your claim is rejected, you can appeal. This is where your documentation becomes your shield. If you were scammed into giving an OTP because the phishing site looked exactly like a government portal, argue that the sophistication of the scam made it indistinguishable from a legitimate request. If the bank remains firm, your next stop is the Financial Industry Disputes Resolution Centre (FIDREC). This is an independent body in Singapore that helps resolve disputes between consumers and financial institutions. They are incredibly helpful for expats who feel they are being stonewalled by a large local bank.
While dealing with the immediate fallout, don't forget the long-term implications. If a large sum of money is tied up in a dispute, it can affect your Budgeting in Singapore: Cost of Living Benchmarks for Expats. You may need to shift funds from investment accounts or your Choosing a Stock Brokerage in Singapore: IBKR, Saxo, and Local Banks portfolio to cover immediate expenses like rent. It is also wise to consult with professionals like Taxes for Expats if the fraud involves significant losses that might impact your reported income or financial standing across borders, especially if you need to prove a loss of funds to tax authorities in your home country.
How to Harden Your Financial Defenses in Singapore
Once you have survived a fraud event, you will likely be looking for ways to ensure it never happens again. The first step is to manage your transaction limits. Most Singaporean banks allow you to set a daily "Online Purchase Limit" via the app. Set this to a low amount, like $500. If you need to make a big purchase, you can temporarily raise it and then lower it immediately after. This limits the "max damage" a fraudster can do even if they get your card details.
Another veteran move is to use a secondary account for online shopping. Keep your main "salary" account with a local bank like OCBC or DBS, but use a multi-currency platform like Wise for your day-to-day digital transactions. By only keeping a few hundred dollars in your digital wallet, you effectively "air-gap" your main savings from the risks of the internet. If that card gets compromised, your rent money and your Singapore Income Tax for Foreigners: IRAS Rules and Filing (2026) provisions remain safe in your primary account.
Finally, keep your contact details updated. Many expats change their phone numbers or forget to update their address when they move between condos. If the bank can't reach you with a warning SMS because you are using an old SIM card, you might miss the chance to stop a fraudster in time. Ensure you can always access your accounts, and if you ever find yourself locked out, follow the steps for How to Retrieve Your Bank Security Token If Locked Out Overseas to regain control. Being proactive is the difference between a minor inconvenience and a financial catastrophe.
Long-term Financial Health and Recovery
Recovering from fraud isn't just about getting the digits back in your account; it is about rebuilding trust in the local system. Singapore’s banking infrastructure is world-class, but it moves fast, and the "Kiasu" (fear of losing out) culture extends to how banks protect their own interests. Stay diligent and keep learning. For example, if you are a new arrival, checking your Expat Health Checklist for the First 30 Days in Singapore should also include a deep dive into your bank’s security settings.
Remember that you are part of a massive expat community here. We share these stories not to scare each other, but to arm each other with knowledge. Whether you are navigating the complexities of the Singapore Healthcare System for Expats: Complete 2027 Guide or just trying to pay for your groceries without getting hacked, the key is to stay alert and never click on a link in an unsolicited SMS. Your financial peace of mind in this beautiful tropical hub depends on your willingness to be just a little bit more skeptical than the average person.
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute legal or financial advice. Banking regulations and fraud policies in Singapore are subject to change. Always consult directly with your financial institution and the Monetary Authority of Singapore for the most current guidelines.