Why Expats Are Excluded from MediShield Life and CPF Subsidies
The moment you receive your first medical bill in Singapore as an Employment Pass holder, the "sticker shock" can be genuinely destabilizing. I remember sitting in a waiting room, looking at a bill three times higher than my local friend's for the exact same consultation. This guide explains why foreigners are excluded from MediShield Life and CPF subsidies, helping you navigate the financial realities of the local system.
The Tiered Reality of Singaporean Healthcare
Singapore’s healthcare system is world-class, but it is fundamentally designed as a tiered structure that prioritizes citizens and permanent residents. When you first arrive, it is easy to assume that because you are paying taxes and contributing to the economy, you might have access to the same safety nets as your local colleagues. However, the administrative line is drawn very sharply at residency status.
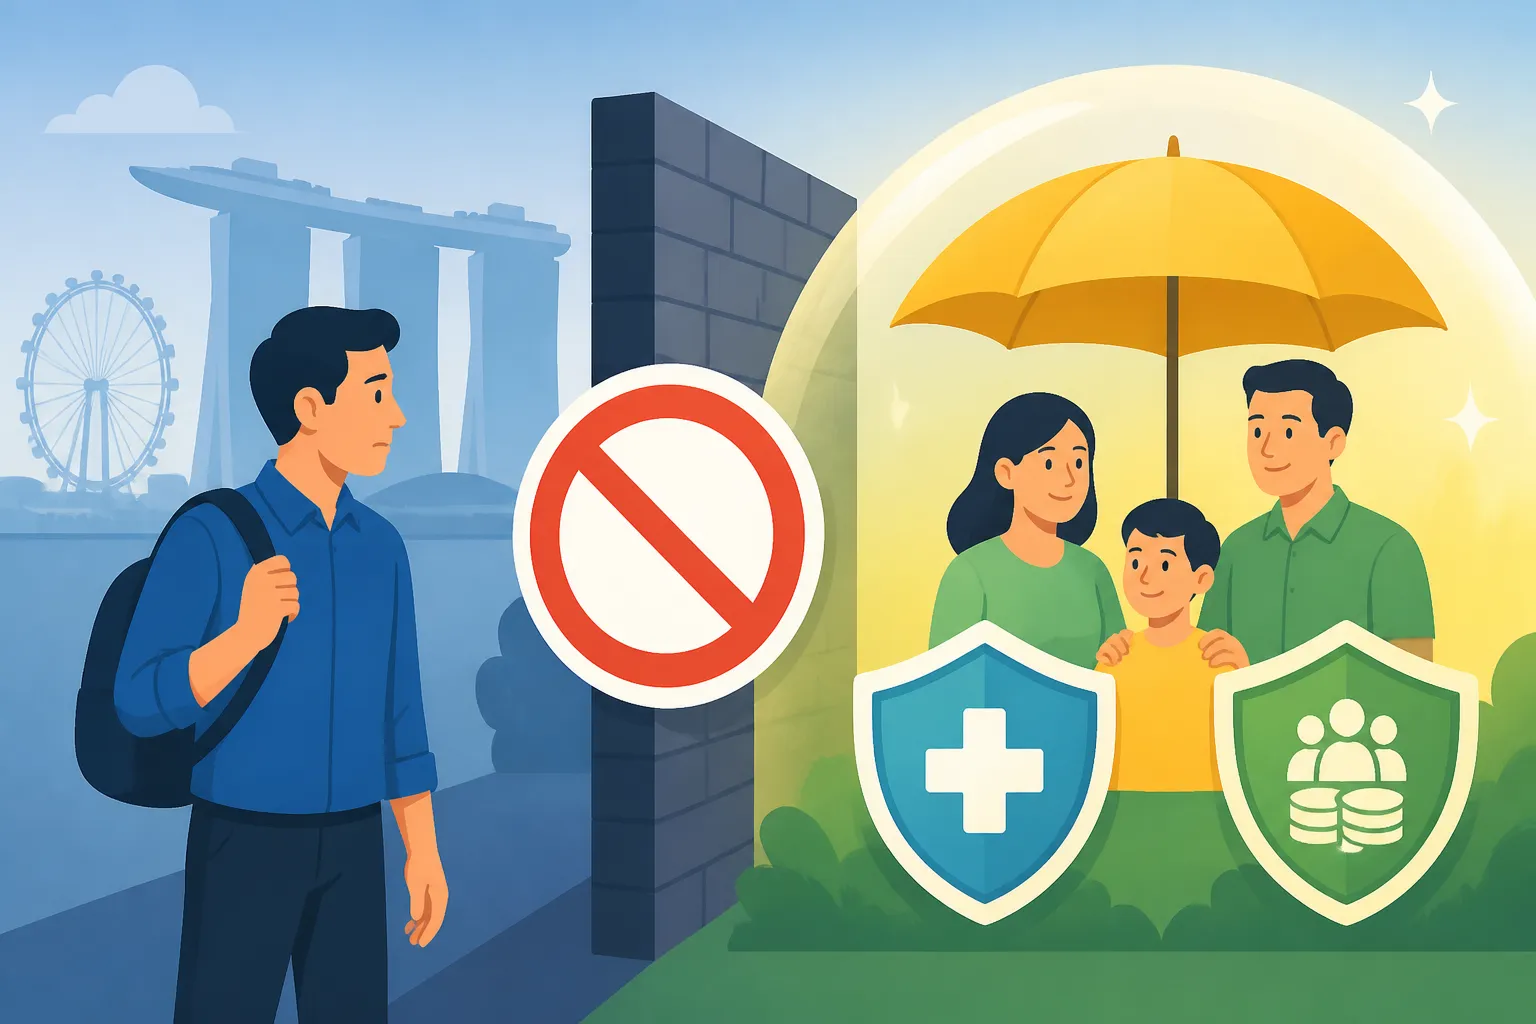
The exclusion of expats from government-backed schemes like MediShield Life is not an oversight; it is a core feature of the city-state's social contract. For locals, healthcare is viewed as a shared responsibility between the individual and the state, funded through lifelong contributions to the Central Provident Fund (CPF). As a foreigner on a work pass, you are outside of this "closed-loop" system.
To understand your position, you must first look at the Singapore Healthcare System for Expats: Complete 2027 Guide. It details how the Ministry of Health (MOH) categorizes patients. As a non-resident, you are billed at the "Full Rate" or "International Rate" at all public institutions. This means that while a Singaporean might see a 50% to 80% subsidy on their hospital ward or surgical procedure, you will be responsible for the 100% undiscounted cost.
Understanding MediShield Life: The Fortress for Locals
MediShield Life is a basic health insurance plan that provides lifelong protection for all Singapore Citizens and Permanent Residents. It is designed to cover large hospital bills and selected costly outpatient treatments, such as dialysis or chemotherapy. The reason you cannot "opt-in" to this plan as an expat is that it is inextricably linked to the CPF system.
Who Qualifies and Why You Do Not
The qualification criteria for MediShield Life are strictly based on legal status. Only those with a pink NRIC (Citizens) or blue NRIC (Permanent Residents) are automatically enrolled. The scheme is "universal" for them, meaning even those with pre-existing conditions are covered. However, the premiums are paid using Medisave, a specific branch of the CPF.
Because most expats on Employment Passes or S Passes do not contribute to CPF, they lack the funding mechanism to pay for MediShield Life. Even if you were willing to pay the premiums in cash, the government maintains this exclusion to ensure the risk pool remains sustainable for the local population. If you are currently evaluating your options, understanding Expat Health Insurance in Singapore: Public vs Private Coverage is the first step toward building your own safety net.
The Role of the Central Provident Fund
The CPF is a mandatory social security savings scheme for locals. A significant portion of a local worker's salary (and an employer's contribution) goes into a Medisave Account. These funds can be used for hospital stays, day surgeries, and even certain outpatient scans.
Expats are generally exempt from CPF contributions. While this means more "take-home" pay in your pocket at the end of the month, it also means you have zero balance in a government-mandated medical savings account. This is a primary reason Why Expats Are Excluded from MediShield Life and CPF Subsidies—without the contribution, there is no corresponding benefit. You are effectively expected to be self-sufficient or covered by private arrangements like those provided by Cigna Global.
The Sticker Shock: Paying Full Rates as a Foreigner
When an expat visits a public hospital, they are often surprised to find that the costs can rival, or sometimes exceed, private clinics in their home countries. This is because public hospitals in Singapore operate on a cost-recovery basis for non-residents.
Public Hospital Billing for Non-Residents
In a public hospital like Singapore General Hospital (SGH) or Tan Tock Seng, wards are divided into classes: A, B1, B2, and C. Locals who choose B2 or C wards receive massive subsidies. However, as a foreigner, you are generally only eligible for Class A or B1 wards, and even if you were to stay in a C-class ward, you would still pay the non-subsidized rate.
The price difference is staggering. For a routine procedure like an appendectomy, a subsidized citizen might pay S$1,500 out of pocket. An expat in the same hospital could easily see a bill exceeding S$10,000. This is why Healthcare Budgeting in Singapore: Managing Out-of-Pocket Costs is such a critical topic for newly arrived families. Without the buffer of MediShield Life, every dollar on that bill comes directly from your insurance or your savings.
Why Your EP Salary Does Not Buy Subsidies
There is a common misconception among high-earning expats that their high tax bracket entitles them to some form of medical subsidy. In reality, income tax in Singapore is kept relatively low compared to Europe or North America specifically because the state does not provide "free" universal healthcare to all residents.
Your Employment Pass allows you to live and work here, but the government’s stance is that your employer must bear the responsibility for your medical costs, or you must insure yourself. This is why many expats turn to comprehensive international providers like Cigna Global to ensure they have the same level of protection that a local would get through the state.
| Service Category | Singapore Citizen (Subsidized) | Expat / Non-Resident (Full Rate) |
|---|---|---|
| Polyclinic Consultation | S$15 – S$25 | S$60 – S$100 |
| Emergency Room (A&E) | S$120 – S$150 | S$400 – S$600+ |
| Specialist Outpatient (SOC) | S$40 – S$90 | S$150 – S$300+ |
| Ward Charges (Per Day) | S$30 – S$100 (Class C) | S$300 – S$800+ (Class A/B1) |
| Standard Day Surgery | 20% – 40% of total cost | 100% of total cost |
Navigating the Gaps in Your Employer Coverage
Most expats rely on the insurance provided by their company. While this is a great perk, it often creates a false sense of security. Corporate plans in Singapore frequently have "inner limits"—caps on specific types of treatments or room rates—that are far below the actual cost of care for a non-subsidized foreigner.
The Limitations of Basic Corporate Insurance
Many expats assume their company plan was "platinum" level, only to find out it only covered S$15,000 for inpatient care per year. In the world of Singaporean private medicine, S$15,000 can be wiped out in two days of intensive care.
If your employer's plan is insufficient, you may need a top-up. Brands like SafetyWing offer flexible options for those who might be moving between countries or who need a more modern, digital-first approach to health coverage. It is vital to read the fine print and Understanding Your Employer’s Medical Benefits Package Before Signing so you aren't left holding a five-figure bill for a sudden illness.
Why Portable Private Insurance is Essential
Another danger of relying solely on your employer is the lack of "portability." If you lose your job or decide to change companies, your medical coverage usually ends the day your last paycheck is cut. If you develop a chronic condition while on a company plan and then try to buy your own insurance later, that condition will likely be excluded as a "pre-existing condition."
This is where a personal policy from a provider like Cigna Global becomes invaluable. It stays with you regardless of your employment status. Having your own plan ensures that your Expat Health Insurance Portability: Keeping Coverage When You Relocate remains intact, protecting your future insurability.
The Strategy for Primary Care: Polyclinics vs. Private GPs
Even for day-to-day issues like a cough or a fever, the lack of subsidies changes the math. Locals go to Polyclinics because they are heavily subsidized. For an expat, the cost of a Polyclinic visit is often similar to a private General Practitioner (GP) because you aren't eligible for the "community" rates.
The Polyclinic Experience for Expats
You can certainly visit a Polyclinic, but you will pay the non-resident rate. Furthermore, Polyclinics are often very crowded, with wait times that can stretch into hours. If the cost is roughly the same, most veterans of the Singapore expat life will tell you to find a reliable private GP near your home or office.
Understanding the Polyclinic vs Private Clinics: Waiting Times and Cost Differences will help you realize that "public" does not always mean "cheaper" for you. In fact, many private clinics offer corporate rates or "foreigner-friendly" packages that might actually be more efficient than the public route.
Managing Chronic Conditions Without MediShield
For those with long-term health needs, the exclusion from MediShield Life is particularly painful. Medications for conditions like hypertension or diabetes are subsidized for locals at public pharmacies. As a non-resident, you pay the full market price.
Some expats find it more cost-effective to ship their regular medications from home (subject to HSA regulations) or to look for international plans that include robust outpatient and maintenance care. If you are in this position, you must be proactive in your Healthcare Budgeting in Singapore: Managing Out-of-Pocket Costs.
Strategic Financial Planning for Medical Emergencies
Since the safety net of the Singaporean government doesn't extend to you, your "safety net" must be your own insurance and an emergency fund. It is wise for expats to keep at least S$10,000 in a liquid "medical-only" emergency fund, even if they have great insurance.
Comparing International Health Plans
When looking for a solution to fill the gap left by MediShield Life, you generally have two choices: a local "IP" (Integrated Shield Plan)—which is usually only available once you get PR status—or a Global International Health Plan.
For current EP holders, the Global Plan is the standard. These plans are designed with the "non-subsidized" reality in mind. They cover high-end private hospitals like Mount Elizabeth or Gleneagles, where wait times are minimal and the care is top-tier. Mentioning providers like Cigna Global is common because they understand the specific billing codes and high costs associated with Singapore's private medical sector.
Why You Should Consider SafetyWing for Transitions
If you are a digital nomad or an expat on a short-term contract, you might not need a massive lifelong plan just yet. In these transitional periods, SafetyWing provides a bridge. It offers a level of flexibility that traditional "heavyweight" insurers sometimes lack, allowing you to maintain coverage while you figure out your long-term residency plans in Singapore.
Remember that Why Are Private Hospitals So Much More Expensive Than Public Ones? is a question of choice. If you don't have the government subsidy, the cost gap between a public B1 ward and a private hospital room is often smaller than you’d think. If you’re paying full price anyway, many choose the comfort and speed of the private sector.
Preparing for a Permanent Residency (PR) Application
Many expats eventually apply for Permanent Residency specifically to gain access to the healthcare subsidies and the CPF system. Once you become a PR, the game changes. You will be automatically enrolled in MediShield Life (after a waiting period and back-payment of premiums in some cases), and you will start contributing to Medisave.
Becoming a PR finally allows you to benefit from the Singapore Healthcare System for Expats: Complete 2027 Guide as a resident. It’s the only way to truly "opt-in" to the local social security net. However, until that PR approval letter arrives in your mailbox, you must operate under the assumption that you are your own insurer.
Final Thoughts on Navigating the Gap
The exclusion from MediShield Life is a tough pill to swallow, especially when you see how smoothly the system works for your local friends. But Singapore is transparent about its rules: the system is designed for citizens first. By acknowledging this reality early, you can take control of your health and finances.
Whether you choose a comprehensive plan from Cigna Global or a more flexible option like SafetyWing, the key is to never be "uninsured" for even a single day. In a country where a major surgery can cost as much as a small car, insurance isn't just a benefit—it’s an absolute survival requirement for the expat community.
Disclaimer
This guide is for informational purposes only and does not constitute legal, financial, or medical advice. Healthcare policies and insurance regulations in Singapore are subject to change. Always verify current rates and eligibility with the Ministry of Manpower (MOM) and the Ministry of Health (MOH) before making significant financial decisions.